Following changes to the legislation governing motor vehicles, certain motorised vehicles may now be subject to compulsory motor third-party liability insurance, even when they are used exclusively on private company premises.
For employers, it is therefore important not only to consider their occupational accident insurance, but also to check whether the motorised equipment used within the business is properly insured.
What has changed for employers?
Since 12 April 2024, Belgian legislation governing compulsory third-party liability insurance for motor vehicles, also known as motor third-party liability insurance, has changed.
One important consideration is that the insurance obligation is no longer exclusively linked to the use of a vehicle on public roads. Certain motorised vehicles used exclusively on private premises may also be subject to compulsory insurance.
This is particularly relevant for businesses that use mobile or motorised equipment. A vehicle does not necessarily have to be used on public roads to require specific motor vehicle insurance.
What does this mean for your occupational accident insurance?
When an employee suffers an accident during and as a result of their work, occupational accident insurance provides cover in accordance with the applicable legal provisions.
If a motorised vehicle is involved in the workplace accident, the insurance covering that vehicle may also play a role. Occupational accident insurance protects the injured employee, but rights of recourse may subsequently arise as part of the financial settlement of the accident.
For some time, there has been uncertainty among many insurers as to whether the necessary cover should be included under a liability policy or a vehicle policy. More recently, we have seen some insurers include the necessary cover for this type of motorised equipment within their liability policies. Others have not yet done so. It is therefore particularly important to check how this is arranged within your own insurance solution, as there may still be points requiring attention depending on the insurer and the specific circumstances.
Which vehicles require particular attention?
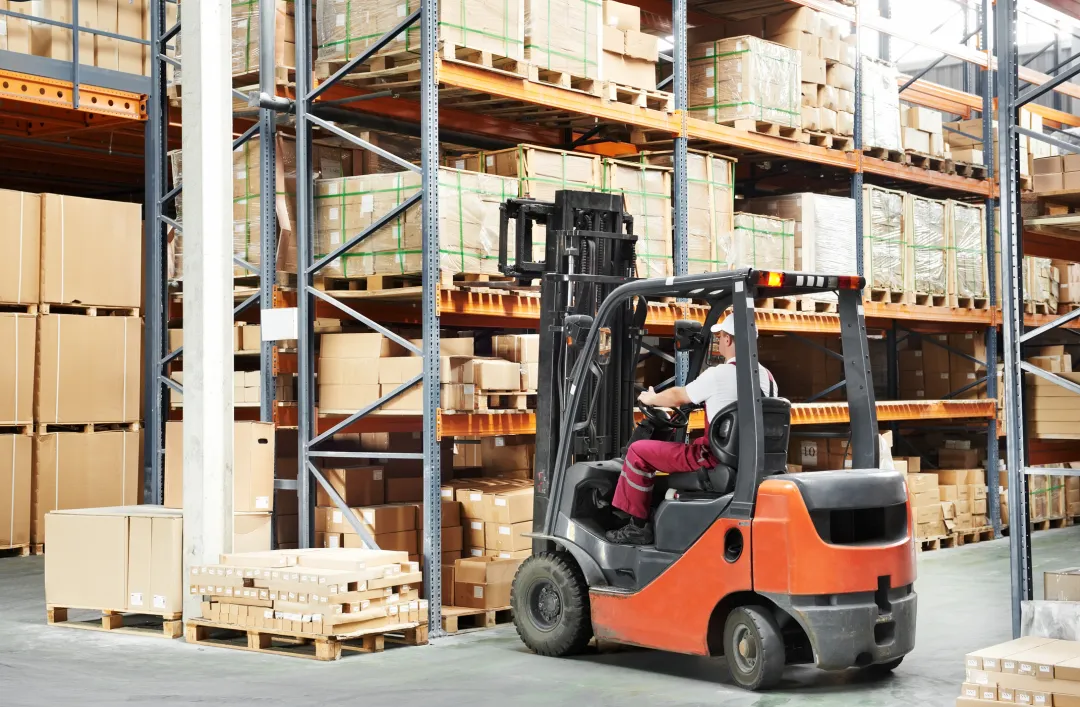
Mobile equipment used exclusively on company premises can easily be overlooked. Examples include forklifts, powered pallet trucks and other self-propelled machinery.
It is therefore important to identify the motorised equipment used within your business and check whether your current insurance cover is still sufficient.
Not every vehicle is automatically subject to the same rules. The assessment depends, among other things, on the type of vehicle, its technical characteristics and how it is used.
Take stock of your mobile equipment
A workplace accident is not the moment to discover that a vehicle should have been insured differently.
Does your business use motorised or mobile equipment? If so, this is a good time to review your insurance arrangements. A simple inventory of the vehicles and equipment in use is the ideal starting point.
Our experts can then review your current insurance policies with you to determine whether they adequately cover the equipment used within your business and whether any additional amendments or clauses are required.
Are you sure your business is properly insured?
The amended regulations make it important to keep an eye not only on your occupational accident insurance, but also on the motorised equipment used within your business.
Do you have a forklift, powered pallet truck or other mobile equipment on your company premises? Contact your trusted account manager at Van Dessel Insurance Brokers. We will be happy to review your current insurance solution with you and check whether it still meets your needs.